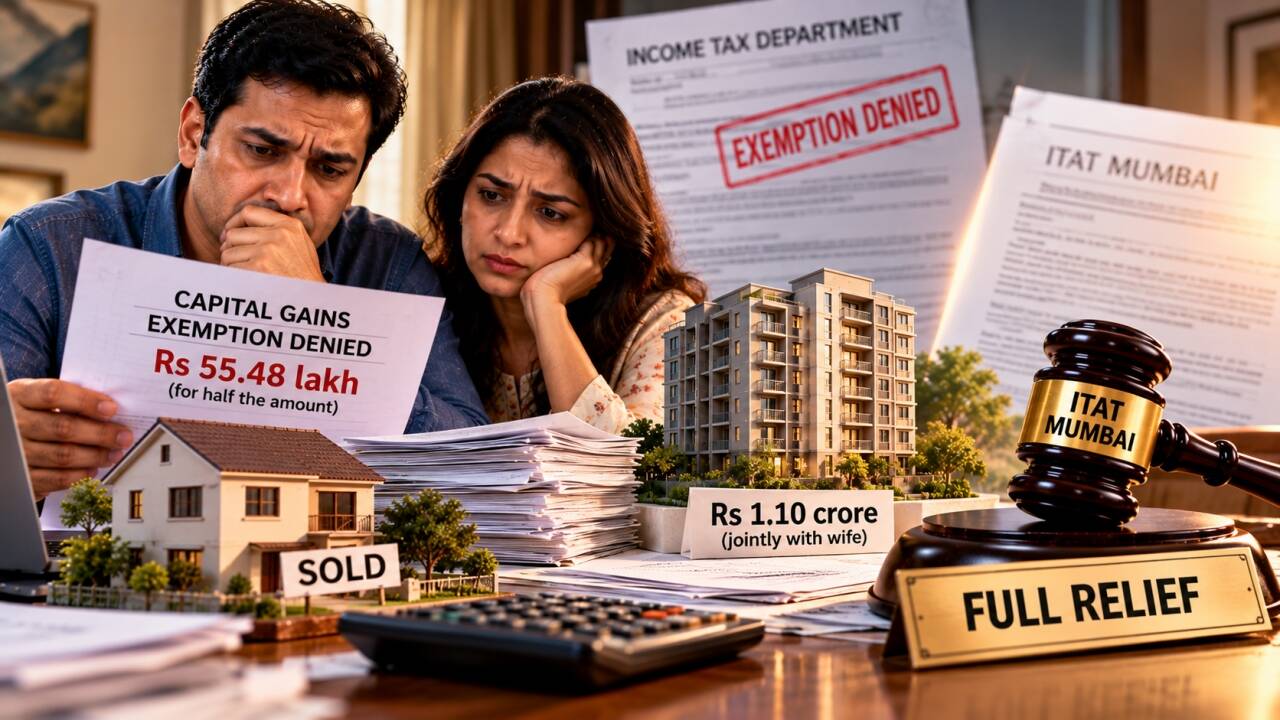
A man sold his residential property and invested the proceeds in another flat in Mumbai. The replacement property was jointly registered in his and his wife's names, with the total investment of around Rs 1.10 crore. He claimed exemption on the capital gains under Section 54 of the Income Tax Act.
Back to Business
Business
October 19, 2026 at 10:38 AM
Sold house, bought Rs 1.10 crore flat with wife; taxman rejects exemption for half the amount
TOI Business
Excerpt from TOI Business.