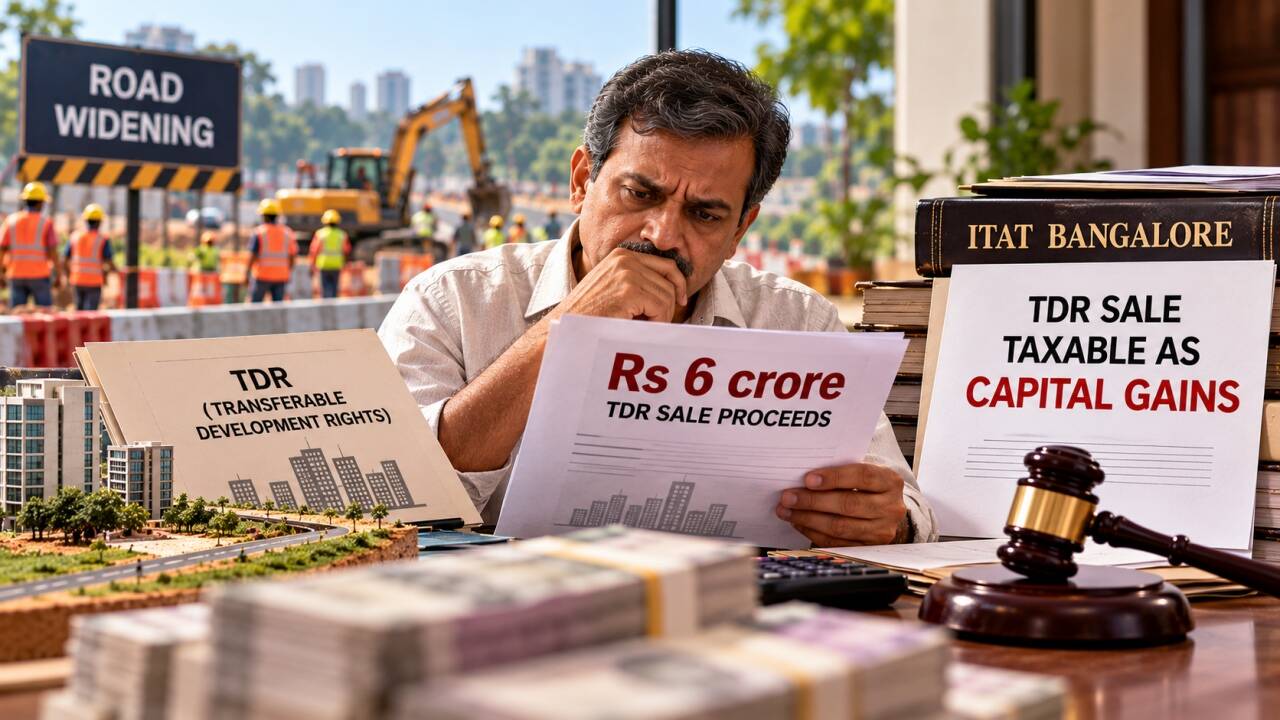
The landowner chose to sell the TDRs he had received for surrendering 2,839 square metres of land. He sold them to a builder for Rs 6 crore but did not pay income tax on the proceeds. His understanding was that the amount received from the sale was a capital receipt and was therefore not taxable.
Back to Business
Business
October 12, 2026 at 5:35 PM
He gave land given for road widening, sold TDRs for Rs 6.02 crore; ITAT taxes capital gains
TOI Business
Excerpt from TOI Business.


